Mortgage Approval Tips With Low Income
Buying a home is one of the biggest financial milestones in life. Unfortunately, many people assume that earning a low income automatically disqualifies them from obtaining a mortgage. Fortunately, that’s not true.
Every year, thousands of borrowers with modest incomes successfully purchase homes by understanding how lenders evaluate mortgage applications. Income is only one part of the equation. Credit history, debt levels, savings, employment stability, and government-backed loan programs all play an important role.
If you’re worried your paycheck isn’t high enough, this comprehensive guide explains exactly how to improve your approval odds while avoiding common mistakes that often lead to rejection.
Why Low Income Doesn’t Automatically Mean Mortgage Denial
Mortgage lenders evaluate risk—not simply salary.
Instead of asking:
“How much money do you make?”
Lenders ask:
- Can you comfortably afford monthly payments?
- Do you pay bills on time?
- Are your debts manageable?
- Do you have stable employment?
- Have you saved enough for emergencies?
A borrower earning $35,000 annually with excellent credit may qualify more easily than someone earning $90,000 with excessive debt.
How Mortgage Lenders Evaluate Applications
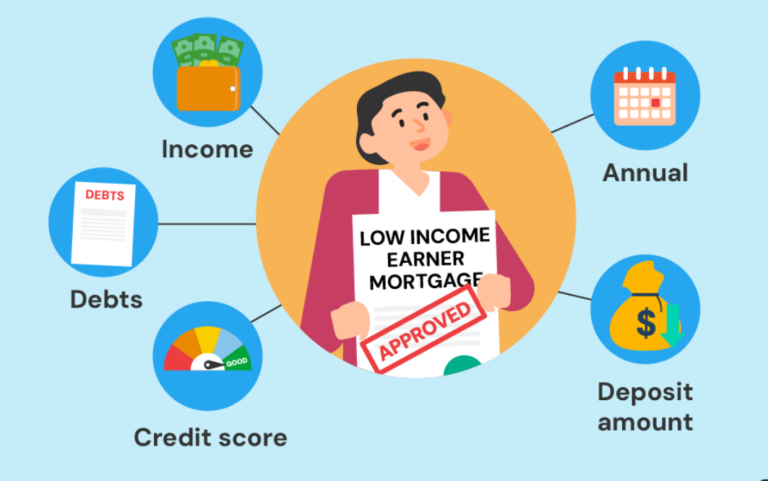
Most lenders focus on five major factors.
1. Income
Income includes:
- Salary
- Hourly wages
- Self-employment earnings
- Bonuses
- Overtime
- Pension
- Social Security
- Disability benefits
- Rental income
Consistent income matters more than unusually high income.
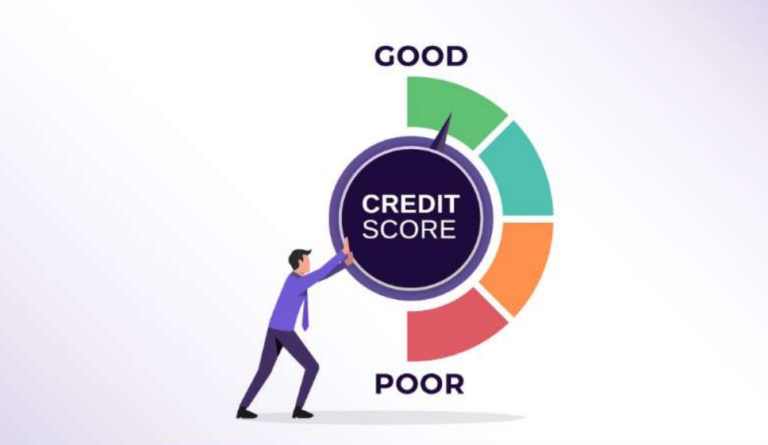
2. Credit Score
Higher credit scores demonstrate responsible financial behavior.
Typical ranges:
| Credit Score | Mortgage Outlook |
|---|---|
| 760+ | Excellent |
| 700-759 | Very Good |
| 680-699 | Good |
| 620-679 | Fair |
| Below 620 | Limited Options |
Improving your score by even 20–30 points can significantly reduce interest rates.
3. Debt-to-Income Ratio (DTI)
Lenders compare:
Monthly Debt ÷ Gross Monthly Income
Example:
Income:
$4,000/month
Debt:
$1,400/month
DTI:
35%
Generally:
- Below 36% = Excellent
- Under 43% = Acceptable
- Above 50% = High Risk
4. Down Payment
Larger down payments reduce lender risk.
Popular options include:
- 3%
- 3.5%
- 5%
- 10%
- 20%
Even a small increase can improve approval chances.
5. Employment Stability
Lenders prefer borrowers who have:
- Two years of consistent employment
- Reliable income
- Minimal employment gaps
25 Mortgage Approval Tips With Low Income
1. Improve Your Credit Score
This is often the easiest way to qualify.
Simple improvements include:
- Pay every bill on time
- Reduce credit card balances
- Avoid late payments
- Correct credit report errors
2. Lower Your Debt
Pay off:
- Credit cards
- Personal loans
- Auto loans
Lower monthly obligations improve affordability.
3. Increase Your Down Payment
Saving just a few thousand dollars more can:
- Lower monthly payments
- Reduce lender risk
- Improve approval odds
4. Avoid New Debt
Don’t finance:
- Cars
- Furniture
- Electronics
Immediately before applying.
5. Choose a Less Expensive Home
Buying below your maximum budget dramatically improves approval probability.
6. Add a Co-Borrower
Combining income with:
- Spouse
- Parent
- Family member
can significantly strengthen your application.
7. Consider Government-Backed Loans
Programs designed for low-income buyers often require:
- Lower down payments
- Flexible credit requirements
- Reduced closing costs
8. Save Cash Reserves
Lenders appreciate borrowers who have emergency savings.
Aim for:
3–6 months of expenses.
9. Reduce Credit Utilization
Keep balances below:
30%
Better yet:
Under 10%.
10. Keep Stable Employment
Changing jobs during mortgage approval may delay or jeopardize your application.
11. Avoid Large Bank Deposits
Unexplained deposits may require documentation.
Maintain clear financial records.
12. File Accurate Tax Returns
Especially important for:
- Freelancers
- Contractors
- Self-employed borrowers
13. Pay Bills Early
Even one missed payment can lower your approval chances.
14. Check Your Credit Report
Dispute:
- Incorrect accounts
- Duplicate loans
- Identity theft
- Collection errors
15. Build Savings Consistently
Small monthly savings demonstrate financial discipline.

16. Increase Income Before Applying
Possible methods:
- Overtime
- Side business
- Freelance work
- Part-time employment
17. Wait Until Existing Loans Are Paid Off
Timing matters.
Waiting six months could dramatically improve approval.
18. Compare Multiple Mortgage Lenders
Different lenders use different underwriting standards.
Shopping around often leads to:
- Better approval odds
- Lower rates
- Reduced fees
19. Avoid Closing Old Credit Accounts
Older accounts strengthen credit history.
20. Keep Documentation Organized
Prepare:
- Pay stubs
- W-2 forms
- Bank statements
- Tax returns
- Identification
21. Limit Credit Inquiries
Too many applications can temporarily reduce your credit score.
22. Budget Carefully
Track:
- Monthly spending
- Savings
- Debt payments
Lenders like financially organized applicants.
23. Improve Your Savings History
Regular deposits demonstrate consistency.
24. Don’t Change Banks During Approval
Maintaining consistent account history simplifies underwriting.
25. Work With an Experienced Mortgage Advisor
Professional guidance can identify programs designed specifically for low-income borrowers.
Common Reasons Mortgage Applications Are Denied
Many denials occur because of avoidable issues:
- Poor credit
- High debt
- Insufficient income documentation
- Job instability
- Large unexplained deposits
- Missed payments
- Insufficient savings
Understanding these factors before applying can significantly improve your chances.
Best Budgeting Tips Before Applying
Successful borrowers typically:
- Build emergency savings
- Pay off credit cards
- Reduce unnecessary spending
- Delay major purchases
- Save consistently
Even six months of preparation can make a substantial difference.
Documents You’ll Need
Prepare these in advance:
- Government-issued ID
- Recent pay stubs
- Tax returns (2 years)
- W-2 or 1099 forms
- Bank statements
- Employment verification
- Debt information
- Asset documentation
Having complete paperwork speeds up approval.
Mistakes That Hurt Mortgage Approval
Avoid these common errors:
- Opening new credit cards
- Financing a vehicle
- Missing bill payments
- Changing jobs unexpectedly
- Spending your down payment savings
- Ignoring credit report errors
- Applying with excessive debt
Frequently Asked Questions
Can I qualify for a mortgage with a low salary?
Yes. Approval depends on multiple factors, including credit score, debt-to-income ratio, savings, employment stability, and the type of loan—not just income.
What credit score is best?
A score above 700 generally qualifies for better interest rates, but some loan programs accept lower scores.
Does a larger down payment help?
Absolutely. A higher down payment reduces the lender’s risk and can improve approval chances while lowering monthly payments.
Should I pay off debt before applying?
In many cases, yes. Reducing debt improves your debt-to-income ratio and may increase the amount you can borrow.
How long should I prepare before applying?
Ideally, spend 6–12 months improving your credit, reducing debt, and building savings before submitting an application.
Final Thoughts
Qualifying for a mortgage on a low income is achievable with careful planning and disciplined financial habits. Focus on improving your credit score, lowering debt, saving for a down payment, and maintaining stable employment. Lenders evaluate your overall financial profile, so strengthening each aspect of your application can significantly increase your chances of approval.
By following these mortgage approval tips with low income, you’ll be in a much stronger position to secure financing and move one step closer to owning your home.