Best Mortgage Lenders for First Time Buyers: Complete Guide
Buying your first home is one of life’s biggest financial milestones. However, choosing among the best mortgage lenders for first time buyers can feel overwhelming because hundreds of lenders offer different interest rates, loan programs, closing costs, and approval requirements.
The good news is that today’s mortgage market offers more options than ever before. Whether you have excellent credit, average credit, or only a small down payment, there is likely a lender designed for your financial situation.
This guide explains everything first-time buyers should know before applying for a mortgage, including loan types, lender comparisons, qualification requirements, common mistakes, and expert strategies to secure the best interest rate.
Why Choosing the Right Mortgage Lender Matters
Many buyers focus only on interest rates.
While rates are important, they are only one part of the total mortgage cost.
A great mortgage lender also provides:
- Fast approval
- Low closing costs
- Helpful loan officers
- Flexible qualification standards
- Excellent customer support
- Digital application process
- Multiple mortgage programs
The wrong lender can cost thousands of dollars over the life of your mortgage.
What Makes a Great Mortgage Lender?
The best mortgage lenders typically offer:
Competitive Interest Rates
Even a small difference of 0.5% can save tens of thousands over a 30-year loan.
Low Down Payment Options
Many lenders allow:
- 3% down
- 3.5% FHA loans
- 5% conventional loans
- VA loans with 0% down
- USDA loans with 0% down
Flexible Credit Requirements
Some lenders approve borrowers with:
- Credit score above 620
- FHA borrowers around 580
- Manual underwriting options
- Alternative income verification
Online Mortgage Application
Digital mortgage platforms make it easier to:
- Upload documents
- Check application status
- Lock interest rates
- Sign documents electronically
Types of Mortgage Loans
Conventional Loans
Ideal for borrowers with:
- Good credit
- Stable income
- Down payment of 3–20%
Advantages include:
- Lower long-term costs
- Flexible loan terms
- Lower mortgage insurance after sufficient equity
FHA Loans
Perfect for first-time buyers because they offer:
- Lower credit requirements
- Down payment as low as 3.5%
- Easier qualification
VA Loans
Available for eligible military members and veterans.
Benefits include:
- No down payment
- No private mortgage insurance
- Competitive rates
USDA Loans
Designed for eligible rural and suburban homebuyers.
Benefits:
- Zero down payment
- Lower mortgage insurance
- Affordable monthly payments
How Much Down Payment Do First-Time Buyers Need?
Contrary to popular belief, you do NOT always need 20%.
Common down payment options include:
| Loan Type | Minimum Down Payment |
|---|---|
| Conventional | 3% |
| FHA | 3.5% |
| VA | 0% |
| USDA | 0% |
Best Mortgage Lenders for First Time Buyers
Here are several lender characteristics worth comparing:
1. Online Mortgage Lenders
Best for:
- Fast approval
- Digital applications
- Competitive rates
Pros
- Lower overhead
- Faster processing
- Convenient document upload
Cons
- Limited face-to-face support
2. Credit Unions
Best for:
- Personalized service
- Lower fees
- Existing members
Pros
- Competitive interest rates
- Lower closing costs
- Strong customer satisfaction
3. Local Community Banks
Great for buyers needing flexible underwriting.
Advantages:
- Personal relationships
- Local market knowledge
- Easier communication
4. National Mortgage Companies
Ideal for buyers seeking:
- Multiple loan products
- Advanced online tools
- Nationwide availability
Credit Score Requirements
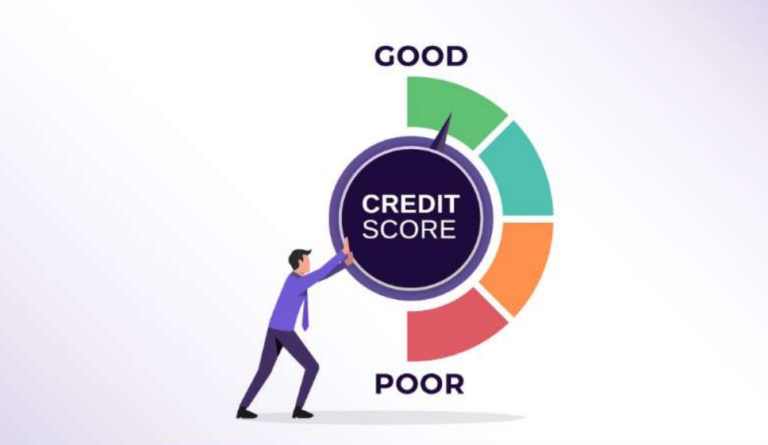
Higher scores generally receive better rates.
Typical ranges:
| Credit Score | Mortgage Outlook |
|---|---|
| 760+ | Excellent |
| 720-759 | Very Good |
| 680-719 | Good |
| 620-679 | Fair |
| Below 620 | Limited options |
Documents You’ll Need
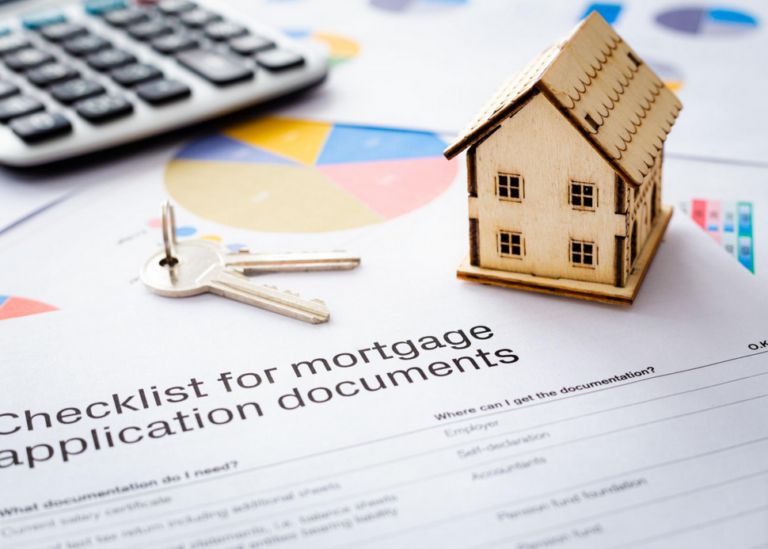
Prepare:
- Government ID
- Pay stubs
- W-2 forms
- Tax returns
- Bank statements
- Employment verification
- Debt information
How Mortgage Interest Rates Work
Rates depend on:
- Credit score
- Debt-to-income ratio
- Down payment
- Loan amount
- Loan term
- Market conditions
Fixed vs Adjustable Rate Mortgages
Fixed Rate
Pros
- Stable monthly payments
- Predictable budgeting
- Long-term security
Best for buyers planning to stay in their home for many years.
Adjustable Rate Mortgage (ARM)
Pros
- Lower initial rate
- Lower early payments
Cons
- Future payment uncertainty
Hidden Mortgage Costs
Remember to budget for:
- Closing costs
- Home inspection
- Appraisal
- Title insurance
- Property taxes
- Homeowners insurance
- HOA fees (if applicable)
Common First-Time Buyer Mistakes
Avoid:
- Applying for new credit during the mortgage process
- Making large purchases before closing
- Changing jobs before approval
- Ignoring closing costs
- Skipping mortgage pre-approval
- Choosing a home beyond your budget
Tips for Getting the Lowest Mortgage Rate
Improve Your Credit Score
Pay bills on time.
Reduce credit utilization.
Avoid unnecessary inquiries.
Save a Larger Down Payment
Higher down payments often reduce:
- Monthly payments
- Interest costs
- Mortgage insurance
Compare Multiple Lenders
Never accept the first mortgage offer.
Comparing multiple lenders can reveal significant differences in rates and fees.
Get Pre-Approved
Pre-approval:
- Strengthens your offer
- Shows sellers you’re serious
- Clarifies your budget
Mortgage Insurance Explained
If your down payment is below 20%, you may pay Private Mortgage Insurance (PMI) on conventional loans.
FHA loans include Mortgage Insurance Premium (MIP), which follows different rules.
Understanding these costs is essential when comparing loan offers.
Should You Buy in 2026?
Buying can make sense if:
- You have stable employment.
- You plan to stay in the home for several years.
- The monthly payment fits comfortably within your budget.
- You have savings for emergencies and closing costs.
Trying to perfectly time interest rates or home prices is often less important than purchasing when your personal finances are ready.
Frequently Asked Questions
Is FHA better for first-time buyers?
It depends. FHA loans can be easier to qualify for, while conventional loans may cost less over time for borrowers with stronger credit.
What credit score is ideal?
A score of 740 or higher generally unlocks more favorable rates, though many buyers qualify with lower scores depending on the loan program.
Can I buy with 3% down?
Yes. Some conventional programs allow 3% down, and FHA loans permit 3.5% down if eligibility requirements are met.
How long does mortgage approval take?
The timeline varies by lender and documentation, but many approvals are completed within several weeks.
Should I get pre-approved before shopping?
Yes. Pre-approval helps define your budget and strengthens your offer when competing for a home.
Final Thoughts
Finding the best mortgage lenders for first time buyers requires more than chasing the lowest advertised interest rate. Compare loan programs, fees, customer service, and qualification standards to find the option that aligns with your financial goals.
By improving your credit, saving for a down payment, gathering documents early, and comparing several lenders, you’ll be better positioned to secure a mortgage that supports long-term homeownership success.